Federal Flood Insurance Program’s Reforms Price Millions Out of Coverage Amid Rising Risks
A flawed federal program, the National Flood Insurance Program (NFIP), is pricing millions of Americans out of flood insurance coverage, despite increasing flood risks nationwide due to climate change. This leaves many homeowners, particularly in areas like eastern Kentucky and…

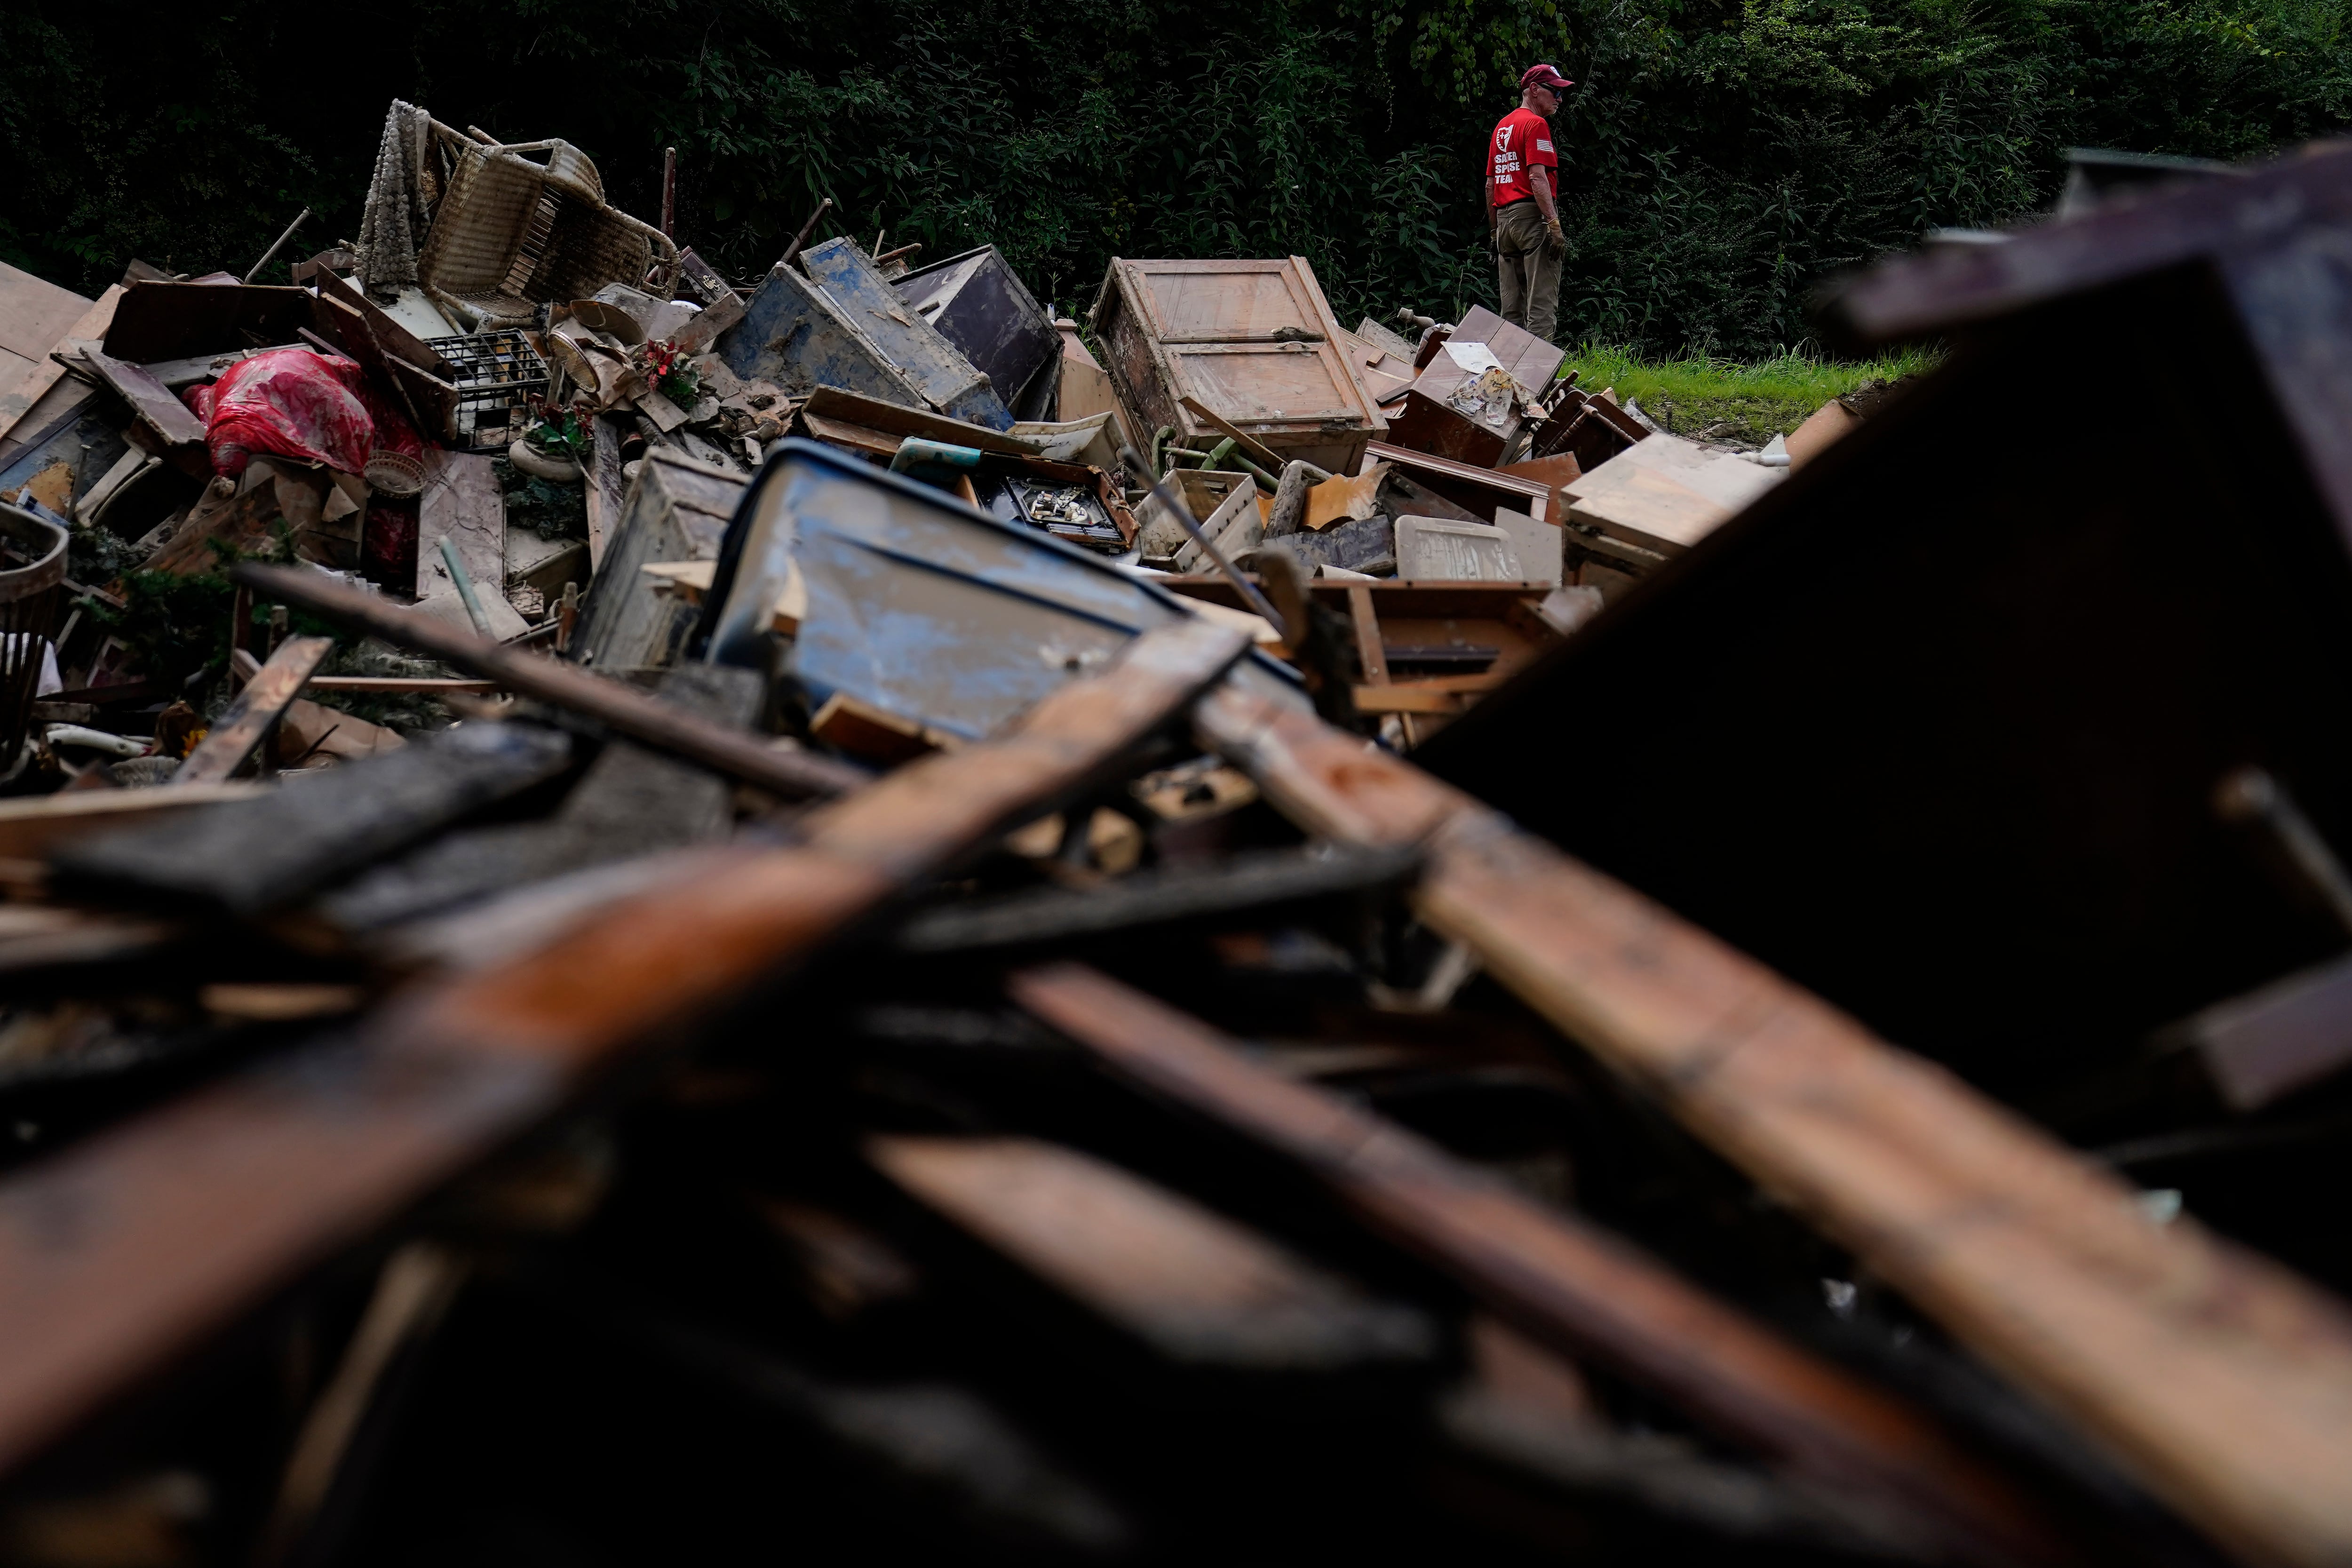
 Philadelphia, PA, September 29, 2026 — The National Flood Insurance Program (NFIP) is facing criticism for pricing millions of Americans out of essential flood insurance coverage, even as flood risks escalate nationwide due to the impacts of climate change. Reforms enacted to bolster the program’s financial stability have resulted in substantial premium increases, creating an affordability crisis for many homeowners.
This situation leaves a significant number of individuals uninsured and exposed to potentially devastating financial losses when flooding events occur. Homeowners in areas identified as particularly vulnerable, such as eastern Kentucky and coastal Louisiana, are among those reportedly affected by these rising costs and subsequent lack of coverage.
The NFIP, administered by the Federal Emergency Management Agency (FEMA), is designed to provide flood insurance to communities that adopt and enforce floodplain management regulations. However, recent efforts to make the program more financially solvent have led to a recalibration of risk assessments and pricing structures. This shift, intended to reflect more accurate actuarial data, has inadvertently made insurance unaffordable for a large segment of policyholders who rely on it for protection against water-related disasters.
The core of the issue lies in the program’s mandate to operate on an actuarially sound basis, meaning premiums should cover expected losses. Historically, the NFIP has been subsidized and operated at a deficit, necessitating legislative reforms to address its financial standing. The latest iterations of these reforms have introduced new methodologies for calculating flood risk, which have, in many cases, led to sharp increases in insurance premiums.
Without adequate flood insurance, homeowners are left to bear the full cost of flood damage. This can range from minor repairs to complete rebuilding costs, often depleting savings and leading to long-term financial hardship. The lack of affordable insurance means that communities in high-risk flood zones are increasingly unprotected, a vulnerability that is amplified by the observed increase in extreme weather events and rising sea levels.
The trend highlights a growing disconnect between the need for flood insurance in an era of heightened climate risks and the practical ability of residents, especially those in financially constrained circumstances, to afford it. The contractor responsible for implementing these changes, or specific details regarding the scale of price increases experienced by policyholders, were not provided. Consequently, many residents in flood-prone regions face an uncertain future, uninsured against a growing threat.
Story summarized from the original created by MICHAEL PHILLIS and M.K. WILDEMAN on www.inquirer.com, see more information here.
Media gallery